FinRL: Financial Reinforcement Learning → FinRL-X




[!IMPORTANT]
FinRL-X is the next-generation evolution of FinRL, designed for AI-native, modular, and production-oriented quantitative trading.
- This repository (
FinRL) preserves the original end-to-end educational and research framework.
- For the latest architecture, live trading deployment, and production-focused development, please use
FinRL-X / FinRL-Trading.
FinRL® is widely recognized as the first open-source framework for financial reinforcement learning.
This repository contains the original FinRL library for education, benchmarking, and research prototyping.
For the next-generation AI-native and production-oriented trading stack, please visit FinRL-X / FinRL-Trading.
FinRL Ecosystem Roadmap
| Generation |
Positioning |
Target Users |
Repository |
Description |
| FinRL-Meta |
Market Environments |
Practitioners |
FinRL-Meta |
Gym-style financial market environments and benchmarks |
| FinRL |
Classic End-to-End Framework |
Learners, Developers, Researchers |
FinRL |
Original train-test-trade pipeline for financial reinforcement learning |
| ElegantRL |
Algorithm Layer |
Researchers and Experts |
ElegantRL |
Lightweight and elegant DRL algorithms |
| FinRL-X |
Next Generation / Production |
Professional traders, institutions, hedge funds |
FinRL-Trading |
AI-native modular infrastructure for deployment-aware quantitative trading |
Recommended for new users: Start with FinRL-X / FinRL-Trading if you are building modern or production-oriented trading systems.
🔄 FinRL-X vs. FinRL: What Changed
| Capability |
FinRL (Stage 1.0) |
FinRL-X (Stage 3.0) |
| Paradigm |
Deep Reinforcement Learning |
AI-Native (ML + DRL + LLM-ready) |
| Architecture |
Three-layer coupled monolith |
Fully decoupled modular layers |
| Strategies |
DRL agents (A2C, DDPG, PPO, SAC, TD3) |
ML selection + DRL timing + extensible base |
| Data Layer |
14 manually-wired processors |
Auto-select: Yahoo Finance → FMP → WRDS |
| Backtesting |
Custom hand-rolled evaluation loops |
Professional bt library engine |
| Live Trading |
Basic Alpaca support |
Full multi-account integration + risk controls |
| Configuration |
config.py + config_tickers.py |
Type-safe Pydantic + .env multi-env |
| Risk Management |
Gym environment constraints only |
Order · portfolio · strategy-level controls |
| Target Users |
Researchers & students |
Quants, institutions, production deployments |
| Paper |
arXiv:2011.09607 |
arXiv:2603.21330 |
FinGPT: an open-source project for financial large language models, designed for research and real-world FinTech applications.


Outline
Project Contributors
FinRL® is an open-source financial reinforcement learning framework developed by contributors from the AI4Finance community and maintained by the AI4Finance Foundation.
Key contributors include:
- Hongyang (Bruce) Yang – research and development on financial reinforcement learning frameworks, market environments, and quantitative trading applications
- [other contributors…]
Overview
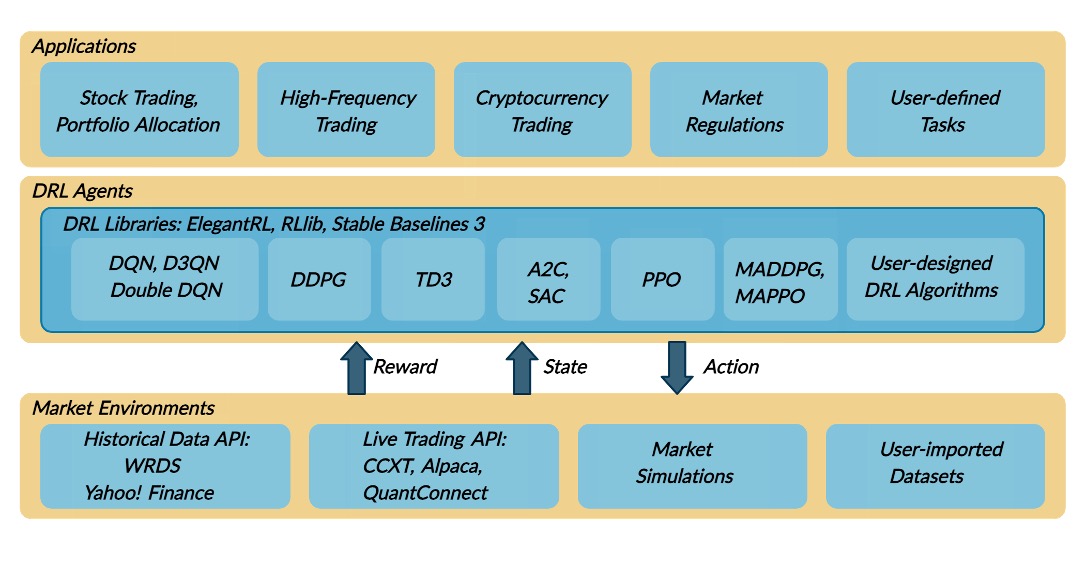
FinRL is the original open-source framework for financial reinforcement learning, organized around three core layers:
- Market Environments
- DRL Agents
- Financial Applications
For a trading task, an agent interacts with a market environment and learns sequential decision-making policies.
This repository focuses on the classic FinRL workflow for education, experimentation, and research prototyping.
For the next-generation production-oriented stack, including modular deployment and AI-native trading infrastructure, please visit FinRL-X / FinRL-Trading.
Videos FinRL at AI4Finance Youtube Channel.
FinRL Stock Trading 2026 Tutorial
This tutorial demonstrates the original FinRL workflow for educational and research purposes.
For the latest production-oriented pipeline, please use FinRL-X / FinRL-Trading.
Step 1: Clone the Repository
git clone https://github.com/AI4Finance-Foundation/FinRL.git
cd FinRL
Step 2: Create and Activate Virtual Environment
python3 -m venv venv
source venv/bin/activate
Step 3: Install FinRL
pip install -e .
Step 4: Run the Scripts
1. Data Download & Preprocessing
python examples/FinRL_StockTrading_2026_1_data.py
This script downloads DOW 30 stock data from Yahoo Finance, adds technical indicators (MACD, RSI, etc.), VIX, and turbulence index, then splits the data into training set (2014–2025) and trading set (2026-01-01 to 2026-03-20), saving them as train_data.csv and trade_data.csv.
2. Train DRL Agents
python examples/FinRL_StockTrading_2026_2_train.py
This script trains 5 DRL agents (A2C, DDPG, PPO, TD3, SAC) using Stable Baselines 3 on the training data. Trained models are saved to the trained_models/ directory.
3. Backtest
python examples/FinRL_StockTrading_2026_3_Backtest.py
This script loads the trained agents, runs them on the trading data, and compares their performance against two baselines: Mean Variance Optimization (MVO) and the DJIA index. Results are printed to the console and a plot is saved as backtest_result.png.
File Structure
The main folder finrl has three subfolders applications, agents, meta. We employ a train-test-trade pipeline with three files: train.py, test.py, and trade.py.
FinRL
├── finrl (main folder)
│   ├── applications
│   	├── Stock_NeurIPS2018
│   	├── imitation_learning
│   	├── cryptocurrency_trading
│   	├── high_frequency_trading
│   	├── portfolio_allocation
│   	└── stock_trading
│   ├── agents
│   	├── elegantrl
│   	├── rllib
│   	└── stablebaseline3
│   ├── meta
│   	├── data_processors
│   	├── env_cryptocurrency_trading
│   	├── env_portfolio_allocation
│   	├── env_stock_trading
│   	├── preprocessor
│   	├── data_processor.py
│       ├── meta_config_tickers.py
│   	└── meta_config.py
│   ├── config.py
│   ├── config_tickers.py
│   ├── main.py
│   ├── plot.py
│   ├── train.py
│   ├── test.py
│   └── trade.py
│
├── examples
├── unit_tests (unit tests to verify codes on env & data)
│   ├── environments
│   	└── test_env_cashpenalty.py
│   └── downloaders
│   	├── test_yahoodownload.py
│   	└── test_alpaca_downloader.py
├── setup.py
├── requirements.txt
└── README.md
Supported Data Sources
| Data Source |
Type |
Range and Frequency |
Request Limits |
Raw Data |
Preprocessed Data |
| Akshare |
CN Securities |
2015-now, 1day |
Account-specific |
OHLCV |
Prices&Indicators |
| Alpaca |
US Stocks, ETFs |
2015-now, 1min |
Account-specific |
OHLCV |
Prices&Indicators |
| Baostock |
CN Securities |
1990-12-19-now, 5min |
Account-specific |
OHLCV |
Prices&Indicators |
| Binance |
Cryptocurrency |
API-specific, 1s, 1min |
API-specific |
Tick-level daily aggregated trades, OHLCV |
Prices&Indicators |
| CCXT |
Cryptocurrency |
API-specific, 1min |
API-specific |
OHLCV |
Prices&Indicators |
| EODhistoricaldata |
US Securities |
Frequency-specific, 1min |
API-specific |
OHLCV |
Prices&Indicators |
| IEXCloud |
NMS US securities |
1970-now, 1 day |
100 per second per IP |
OHLCV |
Prices&Indicators |
| JoinQuant |
CN Securities |
2005-now, 1min |
3 requests each time |
OHLCV |
Prices&Indicators |
| QuantConnect |
US Securities |
1998-now, 1s |
NA |
OHLCV |
Prices&Indicators |
| RiceQuant |
CN Securities |
2005-now, 1ms |
Account-specific |
OHLCV |
Prices&Indicators |
| Sinopac |
Taiwan securities |
2023-04-13~now, 1min |
Account-specific |
OHLCV |
Prices&Indicators |
| Tushare |
CN Securities, A-share |
-now, 1 min |
Account-specific |
OHLCV |
Prices&Indicators |
| WRDS |
US Securities |
2003-now, 1ms |
5 requests each time |
Intraday Trades |
Prices&Indicators |
| YahooFinance |
US Securities |
Frequency-specific, 1min |
2,000/hour |
OHLCV |
Prices&Indicators |
OHLCV: open, high, low, and close prices; volume. adjusted_close: adjusted close price
Technical indicators: 'macd', 'boll_ub', 'boll_lb', 'rsi_30', 'dx_30', 'close_30_sma', 'close_60_sma'. Users also can add new features.
Installation
Status Update
Version History [click to expand]
- 2022-06-25
0.3.5: Formal release of FinRL, neo_finrl is changed to FinRL-Meta with related files in directory: meta.
- 2021-08-25
0.3.1: pytorch version with a three-layer architecture, apps (financial tasks), drl_agents (drl algorithms), neo_finrl (gym env)
- 2020-12-14
Upgraded to Pytorch with stable-baselines3; Removed TensorFlow 1.x support; TensorFlow 2.0 support was under development at the time.
- 2020-11-27
0.1: Beta version with tensorflow 1.5
Tutorials
Publications
| Title |
Conference/Journal |
Link |
Citations |
Year |
| Dynamic Datasets and Market Environments for Financial Reinforcement Learning |
Machine Learning - Springer Nature |
paper code |
51 |
2024 |
| FinRL-Meta: FinRL-Meta: Market Environments and Benchmarks for Data-Driven Financial Reinforcement Learning |
NeurIPS 2022 |
paper code |
136 |
2022 |
| FinRL: Deep reinforcement learning framework to automate trading in quantitative finance |
ACM International Conference on AI in Finance (ICAIF) |
paper |
212 |
2021 |
| FinRL: A deep reinforcement learning library for automated stock trading in quantitative finance |
NeurIPS 2020 Deep RL Workshop |
paper |
275 |
2020 |
| Deep reinforcement learning for automated stock trading: An ensemble strategy |
ACM International Conference on AI in Finance (ICAIF) |
paper code |
426 |
2020 |
| Practical deep reinforcement learning approach for stock trading |
NeurIPS 2018 Workshop on Challenges and Opportunities for AI in Financial Services |
paper code |
303 |
2018 |
News
Citing FinRL
For the next-generation AI-native modular trading infrastructure, see FinRL-X / FinRL-Trading.
@inproceedings{yang2026finrlx,
  title     = {FinRL-X: An AI-Native Modular Infrastructure for Quantitative Trading},
  author    = {Yang, Hongy


 FinRL 是最初的开源金融强化学习框架,可以训练深度强化学习智能体(A2C、DDPG、PPO、TD3、SAC)来交易股票和其他资产。它围绕训练-测试-交易的流程构建,分为市场环境、DRL 智能体和金融应用三大部分。