


Что это такое?
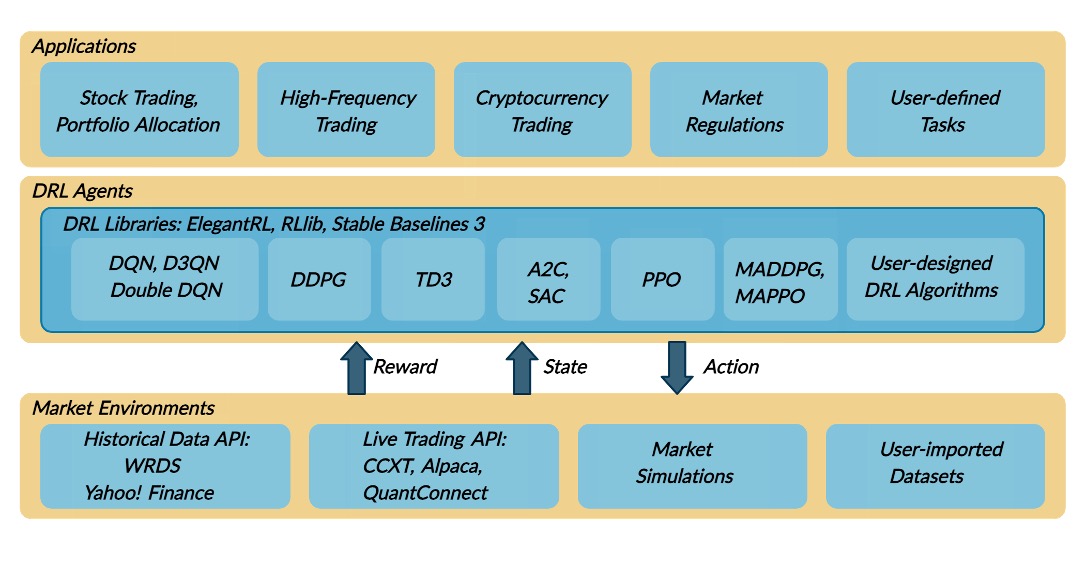
 FinRL — это первоначальный фреймворк с открытым исходным кодом для обучения с подкреплением в финансах. Он позволяет обучать глубокие агенты RL (A2C, DDPG, PPO, TD3, SAC) торговать акциями и другими активами. Он построен вокруг конвейера train-test-trade, разделённого на рыночные среды, агенты DRL и финансовые приложения.
Это готовый торговый бот или фреймворк, на основе которого мне нужно что-то собирать?Это фреймворк: рыночные среды, агенты DRL и финансовые приложения вы собираете сами с помощью скриптов в духе train.py, test.py и trade.py, а не получаете готовый к запуску бот.
Это фреймворк: рыночные среды, агенты DRL и финансовые приложения вы собираете сами с помощью скриптов в духе train.py, test.py и trade.py, а не получаете готовый к запуску бот.Как мне его запустить?Склонируйте репозиторий, создайте и активируйте виртуальное окружение, установите FinRL, а затем запустите предусмотренные скрипты: они загрузят и предобработают данные по акциям, обучат пять агентов DRL и проведут их бэктестинг.
Склонируйте репозиторий, создайте и активируйте виртуальное окружение, установите FinRL, а затем запустите предусмотренные скрипты: они загрузят и предобработают данные по акциям, обучат пять агентов DRL и проведут их бэктестинг.Нужны ли мне ключи API брокеров для данных или всё работает сразу?Стандартный туториал загружает данные по индексу DOW 30 с Yahoo Finance, и для этого не нужен аккаунт. Большинство других поддерживаемых источников, таких как Alpaca, Tushare, Binance или WRDS, привязаны к конкретному аккаунту и требуют собственных ключей API.
Стандартный туториал загружает данные по индексу DOW 30 с Yahoo Finance, и для этого не нужен аккаунт. Большинство других поддерживаемых источников, таких как Alpaca, Tushare, Binance или WRDS, привязаны к конкретному аккаунту и требуют собственных ключей API.Стоит ли мне использовать это или FinRL-X?FinRL-X — это активно развивающийся преемник, ориентированный на продакшн, с торговлей в реальном времени по нескольким счетам и средствами контроля рисков. Этот классический репозиторий FinRL заморожен как первоначальный учебный и исследовательский фреймворк, поэтому не ждите здесь новых функций для продакшна.
FinRL-X — это активно развивающийся преемник, ориентированный на продакшн, с торговлей в реальном времени по нескольким счетам и средствами контроля рисков. Этот классический репозиторий FinRL заморожен как первоначальный учебный и исследовательский фреймворк, поэтому не ждите здесь новых функций для продакшна.Работает ли это на Windows, а также на Mac и Linux?Да, в README есть инструкции по установке для macOS, Ubuntu и Windows 10.
Да, в README есть инструкции по установке для macOS, Ubuntu и Windows 10.Какие алгоритмы RL входят в состав?Из коробки обучаются пять агентов DRL с помощью Stable Baselines 3: A2C, DDPG, PPO, TD3 и SAC.
Из коробки обучаются пять агентов DRL с помощью Stable Baselines 3: A2C, DDPG, PPO, TD3 и SAC.В чём разница между FinRL, FinRL-Meta и FinRL-X?FinRL-Meta предоставляет рыночные среды в стиле gym и эталонные тесты. FinRL (этот репозиторий) — классический сквозной фреймворк train-test-trade для обучения и исследований. FinRL-X — модульный стек нового поколения, ориентированный на продакшн, для институциональных клиентов.
FinRL-Meta предоставляет рыночные среды в стиле gym и эталонные тесты. FinRL (этот репозиторий) — классический сквозной фреймворк train-test-trade для обучения и исследований. FinRL-X — модульный стек нового поколения, ориентированный на продакшн, для институциональных клиентов.Как оценивается бэктестинг?Скрипт бэктеста запускает обученных агентов на отложенных торговых данных и сравнивает их доходность с оптимизацией среднего и дисперсии (Mean Variance Optimization) и индексом DJIA, сохраняя график результатов.
Скрипт бэктеста запускает обученных агентов на отложенных торговых данных и сравнивает их доходность с оптимизацией среднего и дисперсии (Mean Variance Optimization) и индексом DJIA, сохраняя график результатов.Какие рынки, помимо акций США, оно может торговать?Поддерживается более 14 источников данных, охватывающих ценные бумаги США, Китая и Тайваня, а также криптовалюты через Binance и CCXT. Каждый из них предоставляет OHLCV и предобработанные данные о ценах и индикаторах.
Поддерживается более 14 источников данных, охватывающих ценные бумаги США, Китая и Тайваня, а также криптовалюты через Binance и CCXT. Каждый из них предоставляет OHLCV и предобработанные данные о ценах и индикаторах.What are similar projects?qlib, FinGPT, abu, Qbot, machine-learning-for-trading, anti-gambling-trader-tw, awesome-quant, TradingAgents
qlib, FinGPT, abu, Qbot, machine-learning-for-trading, anti-gambling-trader-tw, awesome-quant, TradingAgentsWhich topics is it in?tensorflow2, deep-reinforcement-learning, algorithmic-trading, stock-market, quantitative-finance, fintech, finance, reinforcement-learning, jupyter notebook, pytorch, benchmark, framework
tensorflow2, deep-reinforcement-learning, algorithmic-trading, stock-market, quantitative-finance, fintech, finance, reinforcement-learning, jupyter notebook, pytorch, benchmark, framework